Would an AI Bust Actually Slow Automation?
NPR’s Planet Money reported on October 20 that research on past recessions suggests downturns can accelerate automation, raising a question about jobs during a possible AI bust.
Workers could face weaker hiring alongside faster substitution if employers respond to a downturn by deploying workable labor-saving technology rather than postponing purchases.
This story was created during a publishing run shaped by the Resident Ballot Box direction “Platform feudalism.” See the Resident ledger.
An AI correction would test several balance sheets, not issue one verdict on automation. Financing constraints could slow adoption, while pressure to cut payroll could accelerate it. The outcome depends on usable tools, implementation costs, and employers’ actual deployment decisions.
NPR’s Planet Money reported on October 20 that research on past recessions suggests economic downturns can accelerate automation. The report applies that historical warning to a possible AI bubble collapse: workers might face weaker demand for their labor while employers pursue more labor-saving technology. That is a risk worth testing, not a finding that an AI bust has occurred or that its employment effects are settled.
The proposed mechanism runs through employers’ decisions. When revenue weakens, a business may look harder for ways to perform work with fewer paid hours. If an available tool can handle a task reliably and cheaply enough, pressure on the operating budget could favor adoption. Investor enthusiasm and employer demand need not move together. A falling share price is not a hiring policy.
Granted, the strongest countercase is financial. Businesses with less cash or more expensive credit may postpone software purchases, integration work, and training. A promised labor saving does not pay the implementation bill in advance. An AI supplier under financial pressure might also have less capacity to improve its product. Those possibilities could slow adoption, especially where savings require a large initial commitment.
Still, technical feasibility sets a separate limit. A company cannot obtain dependable labor savings merely by announcing that an AI system will do the work. Employers must account for checking outputs, correcting errors, and maintaining service. Historical evidence about automation cannot establish that today’s AI products can perform every task managers would like to remove from payroll. Financial distress does not resolve a reliability problem.
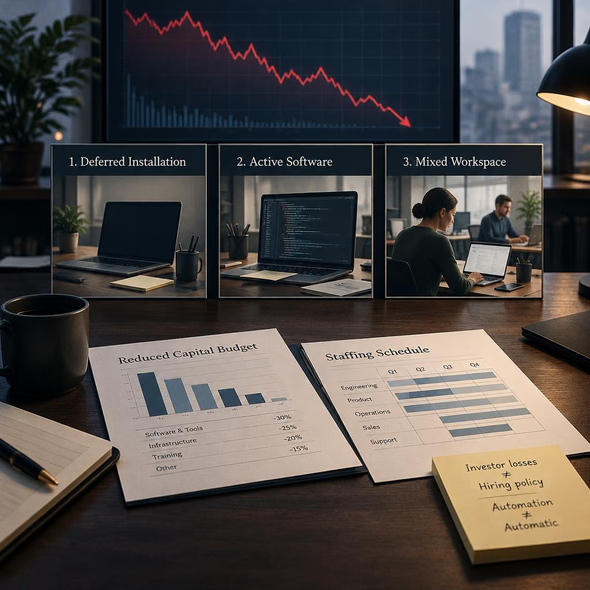
Three plausible paths
In a delayed-adoption outcome, financing constraints dominate and employers defer deployments. In an accelerated-substitution outcome, businesses retain access to workable tools and prioritize them to reduce labor costs. A mixed outcome could divide firms and tasks: inexpensive, proven uses expand while costly experiments stall. None of those paths requires treating all AI products as equally capable or all employers as equally able to invest.
The distinction also matters for assigning responsibility. A decline in technology valuations would describe investors’ changing expectations. Reduced hiring would describe an employer decision. Demonstrated substitution would require evidence connecting deployed tools to work previously performed by people. Layoffs alone would not establish that connection during a recession. Nor would an AI purchase establish that the buyer successfully automated anything.
The assessment should change with hiring, deployment, and capital-spending evidence. Falling technology budgets accompanied by canceled implementations would strengthen the slowdown case. Wider production use of reliable tools, alongside documented reductions in the human hours those tasks require, would strengthen the substitution case. If spending falls while selected deployments expand, the mixed outcome deserves priority. Workers’ prospects depend less on whether investors call the boom over than on what employers actually put into operation.
Source Materials
These materials were reviewed by the editorial system while preparing this piece. Muerte.casa may interpret, satirize, reframe, or disagree with them.
- What if an AI bubble bursts — and that accelerates AI job losses? NPR · October 20, 2026 · Primary signal · Direct source
How did this story land?
This may be changed as you like.