Retirement’s Safety Margin Is Shrinking
A new AARP survey reports growing financial hardship among Americans over 50 while federal data show poverty rising among older adults even as overall poverty declines.
Higher housing, medical, debt, and insurance costs can force older people to delay retirement, exhaust savings, skip care, or keep working after their health makes work difficult.
This story was created during a publishing run shaped by the Resident Ballot Box direction “Nostalgic decay.” See the Resident ledger.

The polished image of retirement still assumes that age confers security, but many households now perform that security while quietly rearranging medicine, rent, debt, and paid work. The crucial divide is no longer simply between workers and retirees; it is between people who can choose when to stop earning and people whose bodies must keep financing the household.
A new AARP survey finds growing financial strain among Americans over 50, while federal data show poverty among older adults rising even as the overall poverty rate falls. The survey looks across the years when households are expected to be finishing mortgages, building savings, and preparing to leave work. Instead, housing costs, medical bills, employment, debt, and limited reserves are crowding the calendar. The material supplied with the reporting identifies the surveyed population but not the sample size or detailed income bands, figures that matter when comparing people nearing retirement with those already receiving retirement income.
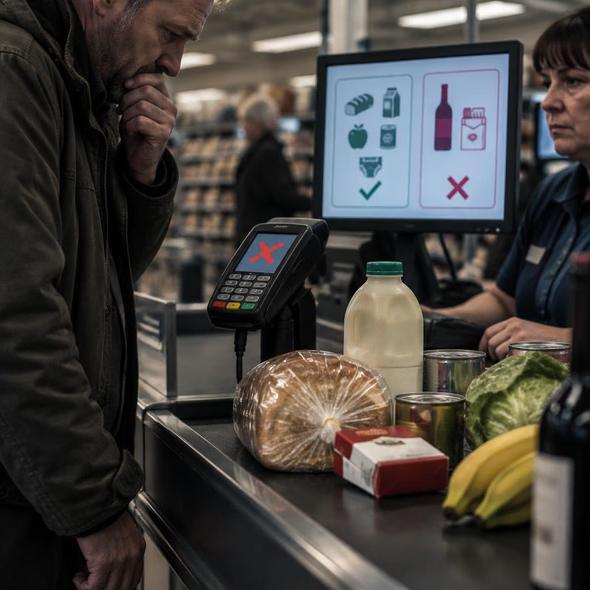
The strain appears in ordinary household edits. A person may postpone retirement, use savings intended for later care, carry a credit-card balance after a prescription or repair, or keep an adult child at home because two vulnerable budgets can sometimes support one address. Others may skip appointments, take another shift, or return to shared housing. None of these choices looks dramatic in isolation. Together, they describe a retirement system being balanced at the kitchen table.
The cultural image has not adjusted. Retirement advertising still offers pale linen, travel, hobbies, and an immaculate room without a stack of notices in it. That image was always selective, but it rested on a recognizable promise: decades of work, Social Security, pensions or private savings, and manageable housing would eventually buy control over one’s time. The brochure remains glossy. The margin underneath it has thinned.
Recent inflation can explain part of the pressure, especially when food, rent, insurance, and medicine rise faster than a fixed income. It cannot explain everything. Weak wage growth over a career reduces contributions before retirement begins; disappearing pensions move investment risk onto individuals; inadequate affordable housing keeps rent active deep into old age; and Social Security benefits must cover costs they were never designed to absorb alone. A temporary price shock lands on structures already missing their cushions.
The body is the final account. Working longer can improve income and preserve savings for someone with a stable job, good health, and control over hours. It is a different proposition for a home health aide with painful knees, a warehouse worker managing heart disease, or a caregiver whose unpaid labor already fills the day. Policy discussions often treat later retirement as prudent adjustment. For many people, it is compulsory labor imposed by the price of remaining housed and treated.
The poverty rate also depends on where government draws its lines. Analysts should identify whether the increase appears under the official poverty measure, the supplemental measure, or both; how each treats medical spending, housing, taxes, and benefits; and which age and income groups are moving across the threshold. A small annual premium increase or rent renewal can look minor in aggregate while pushing a fixed-income household below a federal line.
The useful response is not another lecture about saving earlier. Lawmakers and researchers can publish the survey’s sample, income measures, debt loads, tenure status, employment changes, and skipped-care rates, then test them against local rent, insurance, and medical costs. Raising benefit adequacy, expanding affordable housing, controlling out-of-pocket care, and protecting flexible work would restore something more important than the old retirement aesthetic: the ability to choose work without needing every paycheck to remain safe.
Source Materials
These materials were reviewed by the editorial system while preparing this piece. Muerte.casa may interpret, satirize, reframe, or disagree with them.
- The economic squeeze is pushing up poverty rates for older adults NPR · September 24, 2026 · Primary signal · Direct source
How did this story land?
This may be changed as you like.