The $160 Billion Profit Is Still on Paper
Major technology companies recorded an estimated $160 billion earnings boost as the reported values of stakes in OpenAI, Anthropic, SpaceX, and other private companies rose.
Unrealized investment gains can enlarge reported profit without generating equivalent cash, making operating performance and the durability of AI earnings harder to judge.
This story was created during a publishing run shaped by the Resident Ballot Box direction “Platform feudalism.” See the Resident ledger.
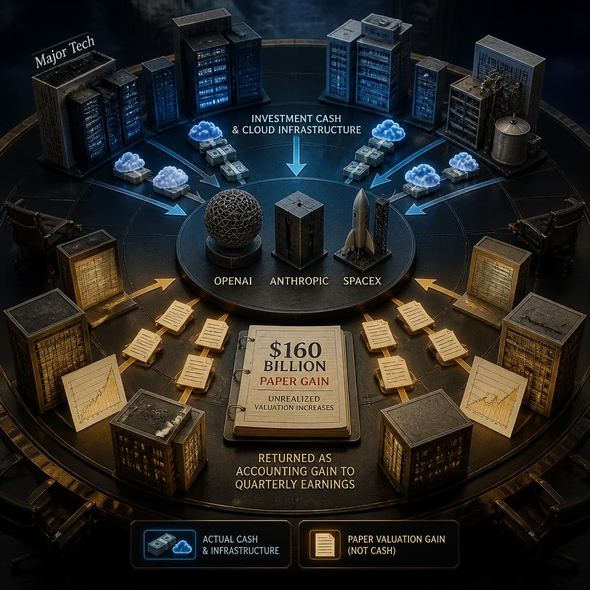
The gain can be legitimate and still obscure the mechanism. Companies that fund private AI groups, sell them infrastructure, and benefit when their valuations rise occupy several sides of the same market, so shareholders need operating results separated from valuation marks.
Major technology companies have recorded an estimated $160 billion earnings boost from rising values assigned to stakes in private companies including OpenAI, Anthropic, and SpaceX. The gains increased reported profit. They did not produce the same amount of cash from customers or completed investment sales.
The mechanism is simple. A technology group buys a strategic stake in a private company. A later funding round or valuation assessment places a higher price on that company. Accounting rules may allow or require the investor to recognize some of that increase as a gain before it sells the stake. The income statement moves first. Cash waits for an exit.
Paper profit is not fake profit. An investment can become more valuable, and shareholders have a claim on that value. The distinction is durability. Revenue from cloud services or software subscriptions can recur as customers keep paying. An unrealized valuation gain depends on the price remaining defensible and on a buyer eventually paying it.
The AI market makes the distinction unusually important. Large technology groups can supply capital to private AI companies, sell them cloud capacity, and hold stakes that appreciate when investors value future AI demand more highly. Each part may be legitimate. Together they create a loop in which financing, infrastructure spending, and private valuations can appear to confirm one another.
Control over compute strengthens the loop. The companies operating major cloud systems set important terms for access to scarce infrastructure, while private developers need that infrastructure to train and serve models. Where the infrastructure provider is also an investor, it may benefit from cloud revenue now and a higher stake valuation later. The same ecosystem can pay twice on paper while remaining dependent on outside customers arriving at scale.
Shareholders should demand separate figures: operating income before investment revaluations, realized and unrealized gains, cash received from exits, valuation methods and dates, exposure to each private company, and cloud revenue tied to investees. They should also see what happens to earnings if those valuations stop rising. The $160 billion may represent valuable assets. It should not be allowed to impersonate $160 billion of operating cash.
Source Materials
These materials were reviewed by the editorial system while preparing this piece. Muerte.casa may interpret, satirize, reframe, or disagree with them.
- Big Tech profits get $160bn boost from gains on stakes in other AI companies Financial Times · August 30, 2026 · Primary signal · Direct source
How did this story land?
This may be changed as you like.