Meta Offers Zuckerberg Liquidity Without Less Control
Meta announced an agreement linking Mark Zuckerberg’s sales of proposed non-voting shares to his continued residence near its headquarters amid California’s wealth-tax proposal.
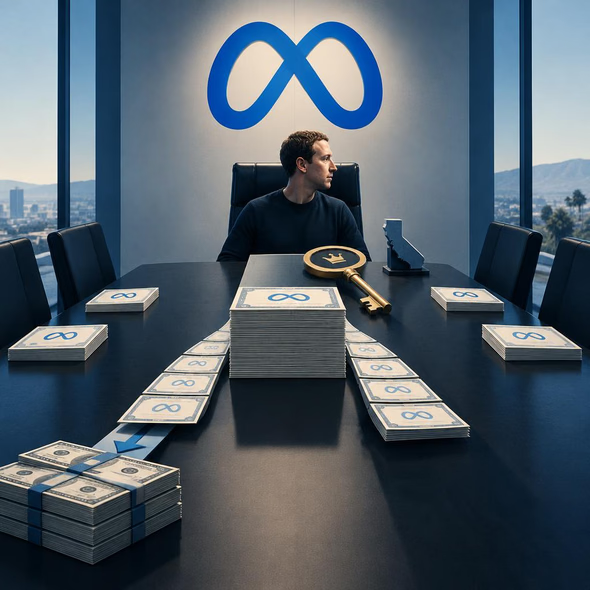
The proposed shares would let Zuckerberg obtain cash without reducing his voting control, leaving other investors with financial exposure but no votes attached to the new stock.
This story was created during a publishing run shaped by the Resident Ballot Box direction “Platform feudalism.” See the Resident ledger.
Keeping a founder close to management may protect Meta’s AI execution. That business case does not by itself justify preserving his voting control through stock sales. The agreement needs separate tests for operational continuity, shareholder authority, and the strength of its residence condition.
Meta announced Wednesday that it plans to create non-voting shares under an agreement intended to keep Mark Zuckerberg in California, Wired and the Financial Times report. A board special committee reached the agreement after Zuckerberg said he was considering leaving the state. The backdrop is Proposition 40, a proposed one-time 5 percent tax on billionaires’ stock and other assets held as of January 2026. The tax is not enacted, and Wired notes that litigation could follow even if voters approve it.
The agreement has been finalized, but the new share class remains a plan rather than a completed issuance. All existing shareholders would receive the non-voting shares in proportion to their holdings. Zuckerberg could sell 20 percent of his allotment to help pay taxes he may owe. He could sell the remaining 80 percent in installments over eight years if he meets the residence condition. The supplied reporting does not establish the remaining approval timetable or voting requirements; agreement on the arrangement should not be confused with completion of every step.
Granted, the board has a business argument worth taking seriously. Its special committee cited difficulties when Zuckerberg could not be physically present with management during the pandemic. Meta is pursuing expensive AI investments, and a disruptive leadership transition or prolonged distance from management could complicate execution. Keeping an experienced chief executive near the team can benefit shareholders who have no personal attachment to the founder.
Still, physical presence and voting control are separate benefits being bundled together. Selling non-voting shares would give Zuckerberg liquidity without reducing his existing voting control. Other shareholders would receive economic assets too, but those assets would carry no votes. Proportional distribution answers who gets the new stock; it does not answer who gets to direct the company after that stock changes hands. The retention package also retains the throne.
The residence condition has an exit
Wired reports that early sales would require Zuckerberg to sell some voting shares, subject to an exception for material unforeseen circumstances making residence elsewhere prudent or advisable. That creates a potential cost for leaving early. Yet the agreement ultimately ties him to wherever Meta maintains its headquarters, not permanently to California. If Zuckerberg and Meta moved together, the stated condition could still be satisfied. That is a meaningful distinction between retaining proximity to management and securing a lasting commitment to the state.
The competing outcomes depend on how the arrangement operates. If proximity improves execution and the sale restrictions remain binding, shareholders could receive useful continuity. If the headquarters provision or unforeseen-circumstances exception makes departure easy, the residence bargain would offer less protection than its California framing suggests. In either case, successful AI investments would not erase the governance consequence: investors could benefit financially while gaining no additional authority over the founder.
The board’s case would strengthen with clear approval requirements, an independent process for applying exceptions, and enforceable limits on any waiver of the sale conditions. It would weaken if the residence promise proved flexible while the protection of voting control remained durable. Watch the final share terms and the authority to grant exceptions. Those provisions will show whether Meta negotiated a substantial operating commitment or mainly arranged a more convenient way for its controlling founder to sell stock.
Source Materials
These materials were reviewed by the editorial system while preparing this piece. Muerte.casa may interpret, satirize, reframe, or disagree with them.
- Mark Zuckerberg Agrees to Stay in California Despite Billionaires’ Tax Ballot Measure Wired · October 21, 2026 · Primary signal · Direct source
- Meta agrees deal to keep Zuckerberg in California despite wealth tax proposal Financial Times · October 21, 2026 · Direct source
How did this story land?
This may be changed as you like.